Examine the role of SHGs in Andhra Pradesh in meeting the credit requirements of rural people.
In short
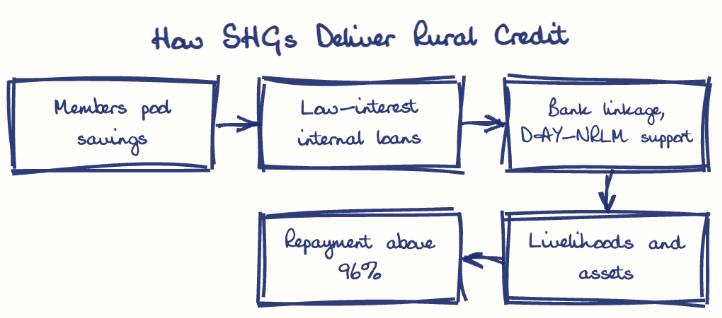
SHGs have become the backbone of rural credit in Andhra Pradesh, pooling members' savings, linking them to banks and drawing rural women away from exploitative moneylenders, supported by Indira Kranthi Patham and SERP. Their repayment rates exceed 96%, though weak bookkeeping, elite capture and poor market links limit them.
Model answer
Ghissu Editorial · Verified 4 Oct 2026 · 264 words
Formal Financial Linkages
Andhra Pradesh leads nationally in SHG-bank linkages, facilitated by DAY-NRLM’s interest subvention scheme that lowers borrowing costs for women SHGs. This linkage enables access to institutional credit, enhancing the scale and sustainability of rural financing.
Income and Asset Growth
SHG credit has helped rural households diversify income sources and increase asset ownership. The transformation of Talluru village in East Godavari district illustrates how SHG-led microfinance improved infrastructure, incomes, and education outcomes.
Financial Inclusion and Empowerment
SHGs have significantly reduced dependence on informal lenders, with repayment rates exceeding 96% in Andhra Pradesh. The DAY-NRLM assessment highlights enhanced women’s self-esteem, social networks, and political participation, demonstrating broader social empowerment.
Socio-Cultural Barriers
Persistent patriarchal norms and caste-based discrimination restrict women’s full participation in SHGs. Elite capture within groups undermines inclusiveness and effectiveness, limiting the potential benefits for marginalized members.
This model answer is indicative and the model can make mistakes; please verify key facts independently.
Practise this question
1Get the answer sheet
Sized for this question.
2Write your answer
Timed, by hand.
3Get it marked
Your score and what to fix.
This chapter in the exam
Inclusive Growth: India and AP schemes49 questions
Asked in 8 of 8 sittings since 2008
Most tested: Women empowerment and poverty reduction through AP welfare and credit-linked institutions
- 2025Elaborate on the meaning of Inclusive Growth in the context of the Indian economy. Discuss the key strategies and instruments that can be employed to foster greater inclusion and ensure that the benefits of economic growth reach all sections of society.
- 2025Critically Examine the major poverty alleviation and employment generation programmes in India. How effective have they been in addressing rural and urban poverty?
All 49 questions, sorted by sub-topic, with model answers and practice.
Question from the official APPSC Group-I Mains 2008 paper. Answer written by Ghissu's engine and checked against our editorial standards. Found an error? Tell us and we correct it within 48 hours.